These are the quantitative trading strategies group projects for FE8827, 2011, Nanyang Technological University.
Chee Tji Hun, Loh Chuan Xiang, Tie JianWang Algernon
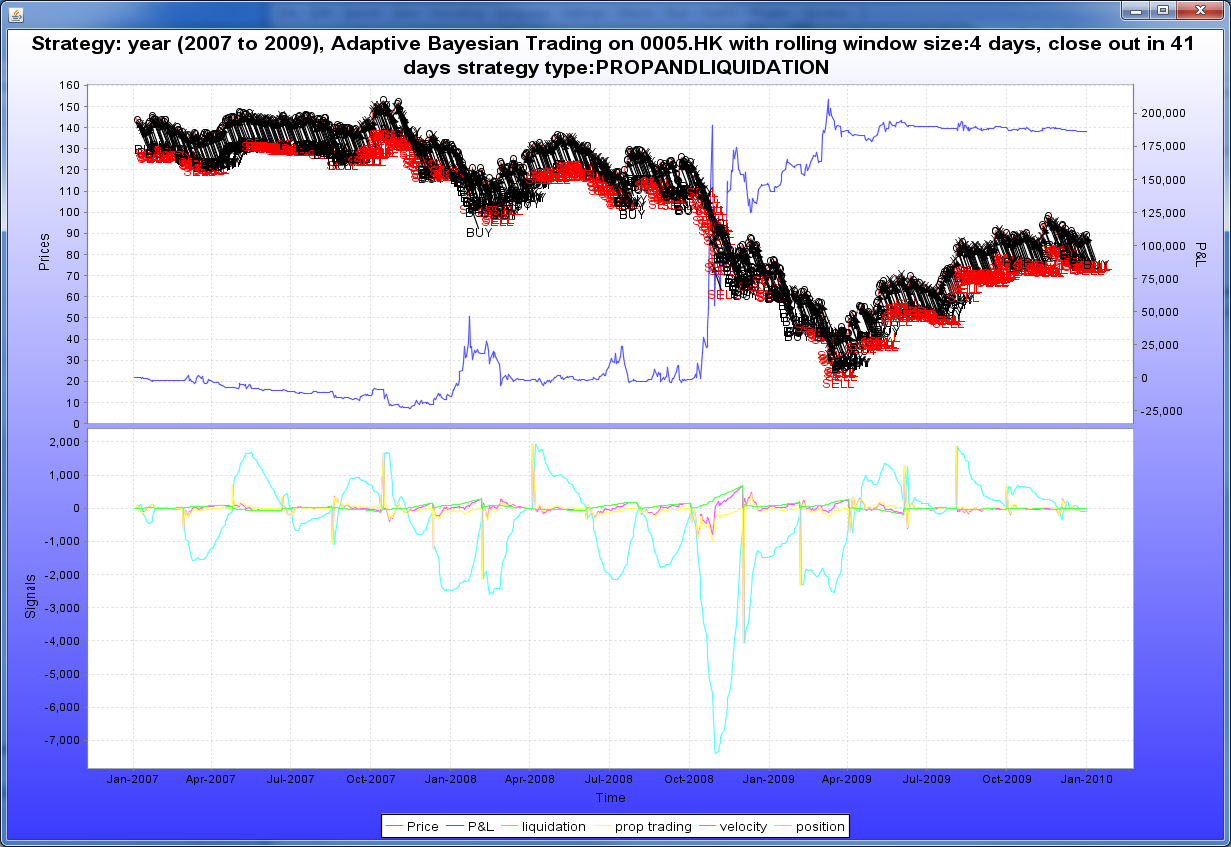
Bayesian Adaptive Trading with a Daily Cycle. Robert Almgren, Julian Lorenz. The Journal of Trading, Fall 2006, Vol. 1, No. 4: pp. 38-46. 2006.
the presentation
Aldwin Shen Weishun, Han Xue, Maurice Tjie, Zeng Fanchaou
Implementation of Pairs Trading Strategies. Oyvind Foshaug. University Van Amsterdam. Koortweg- de Vries Institute for Mathematics. Master of Science Thesis. 2010.
the presentation
the code
Huynh Gia Huy, Le Hoang Thai
Developing High-Frequency Equities Trading Models. Infantino, Leandro Rafael; Itzhaki, Savion. Sloan School of Management, Massachusetts Institute of Technology. 2010.
the presentation
Sinha Prashant Kumar, FU Xiao Hang, Rohan Dhanuka, Magnin Christophe Pierre Thierry
Identifying Small Mean Reverting Portfolios. Alexandre d’Aspremont. 2008.
the presentation
the code
Thursten Cheok Yong Jin, Ng Kok Keong, Kanika Jain
A trading strategy based on the lead�Clag relationship between the spot index and futures contract for the FTSE 100. Chris Brooks, Alistair G. Rew and Stuart Ritson. International Institute of Forecasters, Volume 17, Issue 1, January-March 2001, Pages 31-44. 2001.
the presentation
the code
Seow Kian Ping, Parambill Koyachamveettil Manu Chad, Fang Zhi Heng, Cher Zhong Ming
Statistical Arbitrage in the U.S. Equities Market. Marco Avellaneda, Jeong-Hyun Lee. July 2008.
the presentation
the report
the code
Deng Jie Teo, Ivan Xian, Kenny Tan
Basket trading under co-integration with the logistic mixture autoregressive model. Xixin Chenga, Philip L. H. Yua, W. K. Lia. Quantitative Finance, December 2010.
the presentation
Zhang Leyu, Lorraine Wang Zhi Ren, Lu Xiao, Zhao Xia Jun
Time Series Technical Analysis via New Fast Estimation Methods: A Preliminary Study in Mathematical Finance. Michel Fliess, C\‘edric Join. Quantitative Finance Papers with number 0811.1561. 2008.
the presentation
the code
Suseendra Vigeendhra, Benziger Alice Priyanka, Tiwari Ashutosh Samir, Khair Snehal Prakash
On the short-term predictability of exchange rates: A BVAR time-varying parameters approach. Sarantis, Nicholas. Journal of Banking & Finance, Vol 30, Issue 8, pages 2257-2279. 2006.
the presentation
the code
Note: if you are using IE, somehow, IE renames the extension so you cannot open the .pptx (.docx) file by clicking on it. Please right click to save the file, rename the .zip extension to .pptx (.docx), then open it.